Many people who have trouble budgeting money turn to a simple concept known as the 50/30/20 Rule. How it works: You divide your take-home income each month into three expense categories—50% for essentials…20% savings…and 30% for everything else such as your wants.
50/30/20 has become the gold standard for flexible budgeting strategies because it allows you to allocate your income in a wiser, more balanced way and avoid getting into financial trouble. It is recommended by major companies such as Bank of America and Fidelity, has been widely adopted by financial planners and integrated into popular money apps.
But financial educator and money coach Lynnette Khalfani-Cox, says that “50/30/20 isn’t the best saving strategy for a lot of families. In some circumstances, it actually can amplify your problems.”
We asked Khalfani-Cox how to know if the 50/30/20 rule is the right budgeting system for you and, if not, what others you should consider…
What Is the 50/30/20 Rule?
Two decades ago, US Senator Elizabeth Warren was a Harvard professor studying how families spend money and why some go bankrupt. In a book based on her research, All Your Worth: The Ultimate Lifetime Money Plan, Warren introduced a concept called the 50/30/20 rule. “It became popular especially among beginners,” says Khalfani-Cox, “because it doesn’t require you to constantly monitor your bank account or every single purchase, it prioritizes savings, and you get to spend on fun stuff so you don’t feel deprived.”
How it works…
- 50% of your monthly income is directed to non-negotiable fixed expenses required to live and work. These include rent/mortgage, utilities, groceries, insurance and transportation.
- 30% is for discretionary spending on items that improve your quality of life but aren’t mandatory. Examples: Dining out, entertainment, subscriptions, hobbies and shopping.
- 20% of your income is allotted to securing your future financial health. Examples: Emergency cash fund, retirement accounts, debt payments.
When the 50/30/20 Rule May Not Be the Best Fit
“For people with more complex financial lives, the 50/30/20 rule tends to oversimplify budgeting,” explains Khalfani-Cox. “The broad categories and percentage allocations don’t work well if you live in an expensive area…have a lot of debt…are saving for shorter-term goals such as a wedding or a home purchase…or face other unique life circumstances.”
Budgeting alternatives worth considering instead…
If you have a lot of debt
Allocating just 20% of your income to saving may leave only enough to cover minimal principal repayments on large debts, extending the debt for years and costing thousands in extra interest. The 50/30/20 rule also fails to distinguish between low-interest student loans and high-interest payday or credit card loans, which require a much more aggressive, non-percentage–based approach.
Better: Use short-term austerity budgeting that prioritizes debt reduction and spending cutbacks. Example: Allocate 50% of your monthly income to needs…40% to debt repayment (just make sure you already have a small buffer fund for emergency savings)…and 10% to wants. “This system can work because it temporarily reduces discretionary spending and lowers long-term saving,” says Khalfani-Cox. “If a credit card charges 20% or 25% interest, paying it down faster produces a guaranteed return that beats most yields and returns on savings accounts and investments.”
Caveats to using 50/40/10: Have a clear sense of how long your austerity budget will last to get out of debt. Otherwise, you are likely to lose motivation and feel like you are being permanently deprived.
If you live in a high cost-of-living area
In large cities, rent or mortgage payments/property taxes alone can consume 40% to 50% of take-home pay. Monthly expenses such as utilities, transportation and basic services also are likely to be inflated, so your “needs” category can total 60% or 70% or more of your overall budget.
Better: Unless you plan to downsize your living situation, switch to a system that adapts to your fixed costs. Allocate 60% to needs…20% to savings/debt…and 20% to wants. This provides discipline while keeping savings as a priority and acknowledging higher fixed costs each month.
If you are saving for short-term goals
The 50/30/20 rule doesn’t help you muster the focus or discipline to meet short-term financial goals. And if you don’t reach your target, you could wind up going into high-interest debt to cover the costs.
Better: Use a SMART strategy within your existing budget. Your short-term goal must be…
- Specific—name exactly what you are saving for, such as a used vehicle
- Measurable—set a hard dollar amount, say $18,000
- Achievable—your plan is to save $1,500 a month by reducing your discretionary spending
- Relevant—your wife needs a car for work
- Timebound—it will take you 12 months to save up for the car.
“If the monthly amount feels too tight,” says Khalfani-Cox, “you can make adjustments to your short-term goals by extending the deadline or reducing the amount you want to save.”
If you have unique financial priorities or life circumstances
Dealing with unexpected financial responsibilities, such as helping an elderly parent, requires more flexible financial planning that aligns your money with priorities rather than following rigid formulas.
Better: Priority-based budgeting. “Instead of starting with fixed percentages each month,” says Khalfani-Cox, “this is more personalized budgeting. You rank what obligations matter most to you in descending order and build your budget around that list.”
Alternatives to the 50/30/20 Rule
Sometimes the 50/30/20 rule isn’t right for people because of personal strengths and weaknesses in how they handle money. You know yourself better than anyone else, so choose the budget that works best for you.
Three general budgeting methods that address personal strengths and weaknesses in dealing with money…
Pay-yourself-first budget
Best if: you never seem to be able to save up any money.
How it works: It’s easy to treat savings as an afterthought—whatever is left at the end of the month. This strategy treats your savings as your most important non-negotiable “bill.” First decide your monthly savings goal, then have that amount automatically deposited in a separate account. This reduces your need for will power and discipline. You are forced to structure your living expenses and financial choices to fit whatever remains after your savings target is met each month.
Zero-based budget
Best if: You have trouble keeping track of where all your money goes each month or have irregular income.
How it works: Instead of dividing your money into broad fixed percentages, you assign every single dollar of income from your paycheck to a particular purpose and category. At the end of the month, after you’ve subtracted each expense, your total will be zero. This strategy is highly structured and controlled…and great for staying disciplined and fixing leaks in your spending. You are forced to be very aware of the tradeoffs you make with even small financial decisions.
Envelope budget
Best if: You tend to overspend easily and find it helpful to visualize money with a hands-on system.
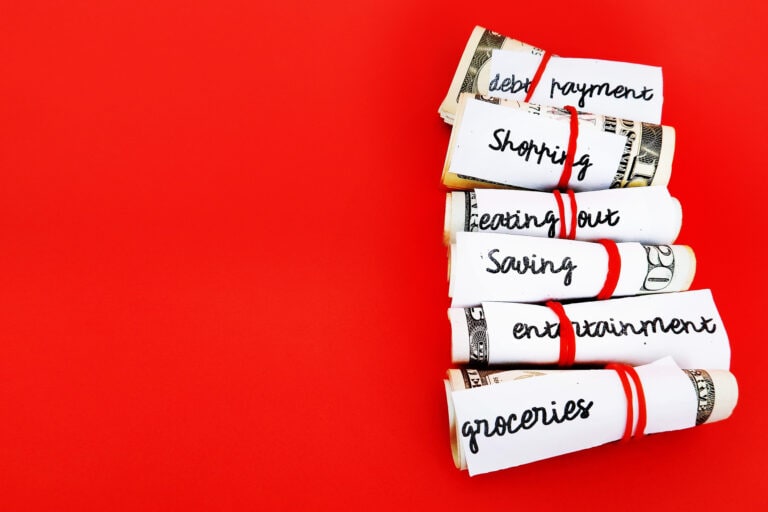
How it works: Also known as “cash stuffing,” you create “envelopes” for each category for the month. When an envelope is empty, spending in the category must stop. This simple method originally used physical envelopes labeled with a name and a dollar amount based on monthly spending categories, but these days you can use digital envelopes in a software program.
How to Choose the Right Budgeting Strategy
“Most people are highly motivated when they start a budget,” says Khalfani-Cox, “but they get easily discouraged as soon as obstacles arise such as emotional spending, the daily drudgery of tracking or unrealistic expectations. In my experiences, the most optimal budget is one you can follow consistently and stick with.” How to determine which budget strategy is best for you…
Track your spending and income closely for several months
Not only does this help you figure out what is most important to you to spend on, it identifies your strengths and weaknesses.
Start with your biggest constraint and pick a method that makes that constraint easier to manage
Example: If you never seem to have money left over for retirement saving, use the “pay yourself first” method to make sure that obligation is never neglected.
Decide how much time and effort you can commit to creating the budget and maintaining it each month
Example: If you are the type who loves making Excel spreadsheets, a zero-based budget method lets you account for every penny.
Experiment with your system for 30 to 60 days
You can tell a system isn’t working if you stop tracking it after a week or two. Rather than abandoning a system, you may just need to make small tweaks. “There’s nothing wrong with using hybrid strategies,” points out Khalfani-Cox. “For instance, you may feel comfortable with a 50/30/20 strategy but also employ an envelope method just for the 30% “wants” category to prevent chronic overspending.”